
How to Calculate Rental Property Cash Flow: A 2026 Investor’s Guide
What if the $500 monthly profit you see on your spreadsheet is actually a $200 deficit waiting to happen in your bank account? For many investors in the Petoskey and Traverse City markets, the gap between "paper profit" and bankable cash is often filled with overlooked maintenance costs and seasonal vacancy fluctuations. We recognize that underestimating these variables can compromise the stability of your entire portfolio. This guide provides a disciplined framework for how to calculate rental property cash flow with the technical precision required for the 2026 market, where investment mortgage rates currently average above 7 percent.
We will move beyond basic estimates to analyze the exact formulas and local data points that define a truly successful investment. You'll gain a clear, repeatable methodology for deal analysis that separates engineering-grade projections from optimistic guesswork. By the end of this article, you'll understand how to distinguish Net Operating Income from actual liquidity. This knowledge provides the confidence to evaluate Northern Michigan properties with a focus on long-term financial integrity and operational efficiency.
Key Takeaways
- Master the standardized 5-step formula for how to calculate rental property cash flow to ensure your financial projections align with actual bankable results.
- Learn to categorize fixed and variable expenses accurately, including the critical allocation for capital expenditures and long-term maintenance reserves.
- Understand the impact of Northern Michigan’s local market variables, such as seasonal vacancy shifts, on your total potential income modeling.
- Identify how professional management systems and maintenance coordination protect your ROI by reducing tenant turnover and preventing costly emergency repairs.
The Fundamentals of Rental Property Cash Flow
Understanding the Fundamentals of Rental Property Cash Flow is the prerequisite for any sustainable real estate operation. At its core, rental property cash flow is the net capital remaining after every operational expense and debt obligation has been satisfied. It's the primary metric we use to gauge the long-term stability of a portfolio. Knowing how to calculate rental property cash flow accurately prevents investors from confusing gross revenue with actual profit.
Investors typically encounter three financial states. Positive cash flow indicates a surplus that can be reinvested or utilized as income. Negative cash flow, conversely, represents a structural deficit where the owner must inject personal capital to maintain operations. This often occurs when debt service or maintenance exceeds the monthly rent. Break-even scenarios provide no margin for safety, leaving the asset vulnerable to insolvency if a single significant repair event occurs.
It's vital to distinguish between cash flow and appreciation. Appreciation is a speculative increase in property value over time, contributing to long-term wealth. Cash flow provides the immediate liquidity needed to sustain the investment. Wealth is theoretical until a sale occurs; income is bankable. Reliable portfolios prioritize consistent monthly yields over the hope of future market spikes.
Cash Flow vs. Net Operating Income (NOI)
Net Operating Income (NOI) serves as a standardized metric for property valuation. It represents the total income minus all operating expenses before any financing or taxes are considered. This allows us to compare the efficiency of different assets regardless of their mortgage structures. Cash flow remains the ultimate measure of personal liquidity because it accounts for debt service. Mortgage payments represent the bridge between a property’s operational performance and its actual cash yield for the owner.
Why 2026 Market Volatility Requires Precise Math
Current market conditions in September 2026 present unique challenges for those investing in rental property Northern Michigan. With investment property mortgage rates currently fluctuating between 6.5% and 8.5%, the margin for error has narrowed significantly. Investors in high-demand areas like Petoskey or Traverse City cannot rely on rough estimates for their overhead. Precise math is mandatory to ensure that high acquisition costs don't result in a negative yield. Learning how to calculate rental property cash flow using verified data rather than optimistic projections is the only way to safeguard a portfolio against shifting interest rates and seasonal occupancy risks.
Step 1: Calculating Your Gross Rental Income
The first stage in identifying how to calculate rental property cash flow involves establishing your Gross Potential Income (GPI). This figure represents the total theoretical revenue your property generates if it remains 100 percent occupied throughout the fiscal year. While GPI serves as a useful baseline for high-level modeling, it rarely reflects the actual liquidity available at the end of the month. To reach a realistic projection, you must transition from GPI to Effective Gross Income (EGI).
This transition requires the application of a vacancy factor. In a structured financial model, we typically subtract 5 to 10 percent from the total income to account for tenant turnover and administrative downtime. Neglecting this step is a common error that leads to inflated expectations. In Northern Michigan, where seasonal shifts influence moving patterns, a conservative vacancy estimate is essential for maintaining capital reserves. EGI is the figure that remains after subtracting this vacancy allowance from your total potential income.
Determining Fair Market Rent in Northern Michigan
Establishing an accurate base rent requires a rigorous analysis of local comparables in markets like Traverse City or Boyne City. We analyze similar units based on square footage, utility structures, and proximity to regional hubs. Seasonal demand significantly impacts these figures. A property in a resort-heavy area may command higher premiums during peak months, but long-term stability depends on setting a rate that remains competitive year-round. Utilizing rental management Charlevoix expertise allows investors to leverage real-time data to set prices that maximize occupancy without leaving revenue on the table.
Accounting for Other Income Sources
A comprehensive cash flow analysis looks beyond the monthly base rent to capture secondary revenue streams. These include:
- Pet Rent: Monthly fees that offset the increased wear on flooring and surfaces.
- Utility Bill-Backs (RUBS): Implementing a Ratio Utility Billing System allows you to recover costs for water, sewer, and trash, directly improving your bottom line.
- Storage and Parking: Monetizing underutilized square footage through dedicated storage units or premium parking spaces.
Capturing these details is critical when learning how to calculate rental property cash flow. Standardized systems ensure that late fees and non-refundable deposits are recorded consistently, preventing "leakage" in your financial reporting. If you need assistance auditing your current revenue streams, our team can provide a professional financial reporting and accounting review to identify missed opportunities for growth.
Step 2: Identifying Operating Expenses and Debt Service
Once you've established your effective gross income, the next phase in how to calculate rental property cash flow is a rigorous audit of your outflows. We categorize these into three primary groups: fixed expenses, variable expenses, and debt service. Maintaining fiscal discipline requires looking beyond the obvious monthly bills to account for the long-term structural costs of property ownership. This granular approach ensures that your projections remain rooted in reality rather than optimism.
Fixed expenses are the predictable baseline costs that remain relatively constant regardless of occupancy. These include property taxes, landlord insurance policies, and any applicable HOA or condo fees. Variable expenses, however, require more sophisticated modeling. These cover routine repairs and ongoing maintenance. Many novice investors rely on the "50% Rule," which suggests that operating expenses will consume half of the gross rent. While useful for a ten-second litmus test, this rule is often too imprecise for professional deal analysis in a high-interest environment.
Debt service represents your total mortgage obligation, specifically the principal and interest payments. While taxes and insurance are often escrowed into this payment, we treat the loan itself as a separate category to better analyze the property's leverage. In 2026, with investment rates often exceeding 7 percent, debt service is frequently the largest single deduction from your revenue stream.
The "Hidden" Northern Michigan Expenses
Investors in Emmet and Charlevoix counties must account for geographic variables that don't appear in national templates. Snow removal is a non-negotiable operational cost that impacts both safety and liability. Winterization of plumbing and HVAC systems is equally critical to prevent catastrophic pipe bursts during sub-zero temperatures. Older homes, common in historic Northern Michigan neighborhoods, often present higher utility costs due to legacy insulation standards. Reviewing our guide on rental property maintenance Northern Michigan provides a structured framework for managing these climate-specific overheads without compromising your margins.
Budgeting for Capital Expenditures (CapEx)
A common pitfall in how to calculate rental property cash flow is failing to distinguish between a minor repair and a capital expenditure. A repair, like fixing a leaky faucet, is an immediate operational cost. CapEx involves the long-term replacement of major systems, such as a roof, boiler, or parking surface. We recommend setting aside a dedicated reserve of 5 to 10 percent of your monthly rent, depending on the asset's age. This reserve acts as a financial buffer, ensuring that a $12,000 roof replacement doesn't result in a year of negative cash flow. This disciplined withholding is what separates "paper profits" from sustainable, long-term liquidity.
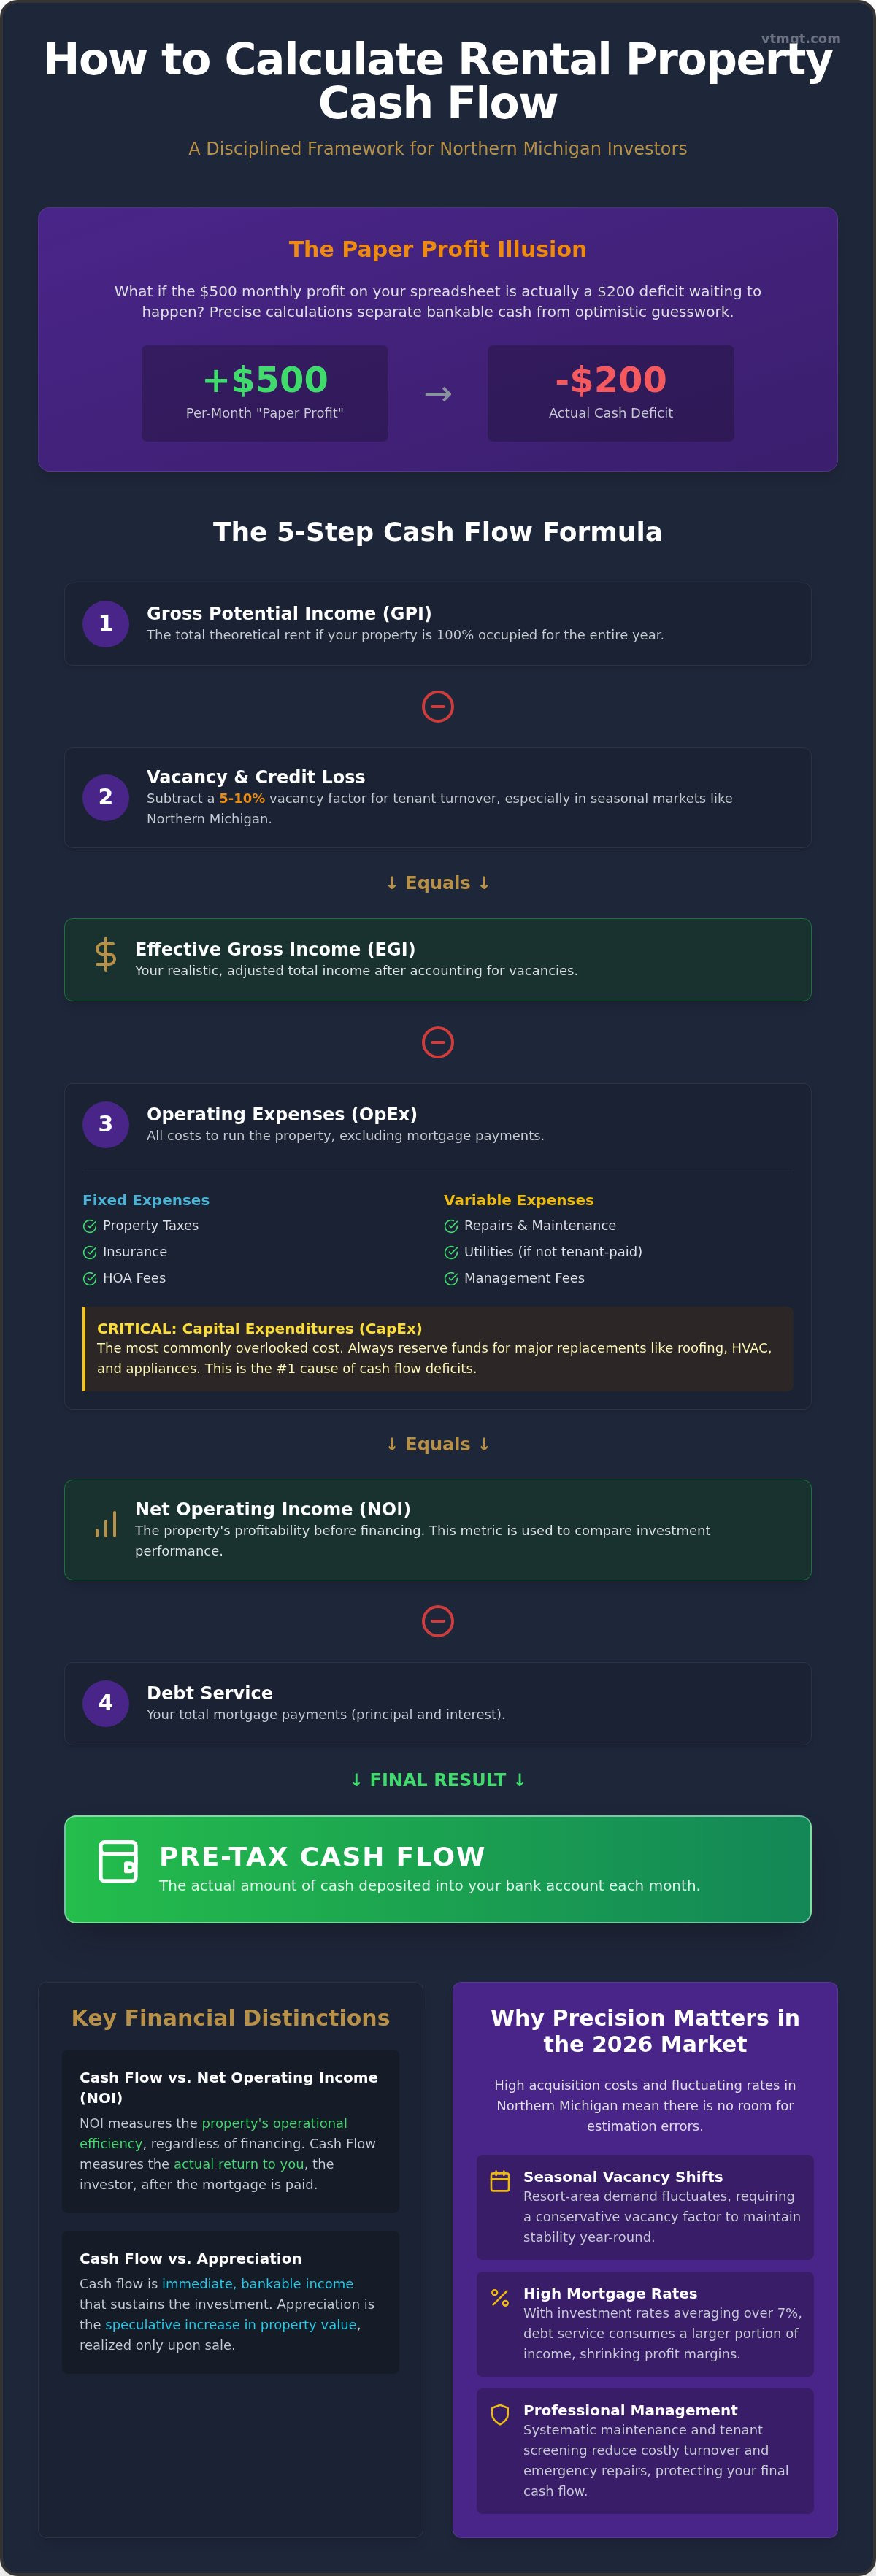
The 5-Step Cash Flow Formula
Mastering how to calculate rental property cash flow requires a standardized sequence of calculations to eliminate speculative errors. We treat each step as a logical progression, ensuring that every financial variable is accounted for before reaching a final liquidity figure. This disciplined methodology allows investors to evaluate different assets on a strictly objective basis.
- Step 1: Gross Potential Rent + Other Income = Total Potential Income. This captures every possible dollar the property can generate.
- Step 2: Total Potential Income - Vacancy = Effective Gross Income (EGI). This reflects the reality of tenant turnover and market friction.
- Step 3: Effective Gross Income - Operating Expenses = Net Operating Income (NOI). This measures the property's operational efficiency before financing.
- Step 4: NOI - Debt Service = Cash Flow. This is the actual surplus that enters your bank account each month.
- Step 5: (Annual Cash Flow / Initial Investment) x 100 = Cash-on-Cash Return. This percentage determines the efficiency of your deployed capital.
Example Calculation: A Petoskey Single-Family Home
To illustrate the process, consider a hypothetical single-family home in Petoskey with a monthly market rent of $2,500. After establishing the base rent, we subtract a 5 percent vacancy factor ($125), resulting in an Effective Gross Income of $2,375. From this, we deduct operating expenses, including a 7 percent management fee ($175), a 10 percent maintenance reserve ($250), and estimated property taxes and insurance totaling $300. These deductions bring the total operating expenses to $725, leaving a Net Operating Income of $1,650. After satisfying a $1,400 monthly mortgage payment, the final bankable cash flow is $250 per month. Without this level of detail, an investor might mistakenly believe they've earned $1,100 in profit simply by subtracting the mortgage from the rent.
Evaluating Cash-on-Cash Return
While capitalization rates (Cap Rates) are useful for comparing property values, the cash-on-cash return is the superior metric for investors using financing. It measures the actual yield on the cash you personally invested rather than the total property value. In the 2026 Northern Michigan market, a "good" return often balances immediate yield with the long-term stability of the asset class. Leverage amplifies your cash-on-cash return by allowing you to control a high-value asset with a relatively small portion of your own capital. If your manual calculations reveal a deficit, our team can provide professional financial reporting and accounting to help you restructure your operational costs for better performance.
Optimizing Cash Flow with Professional Management
While the previous sections detailed the technical aspects of how to calculate rental property cash flow, the long-term performance of an asset depends on operational precision. Professional management isn't merely an administrative expense. It's a strategic tool for protecting your Net Operating Income. In the 2026 market, where national management fees average 8.49 percent of collected rent, the value is found in standardized systems that reduce vacancy and mitigate risk.
Aggressive marketing and professional tenant screening ensure that units remain occupied by qualified residents, directly supporting your Effective Gross Income. Many investors attempt "sweat equity" to save on fees, but this approach often results in hidden costs. A single month of vacancy due to poor marketing or a legal error regarding Michigan landlord laws can quickly erase the perceived savings of DIY management. Professional oversight ensures that lease agreements and security deposit returns are handled with engineering-grade accuracy.
Leveraging Local Expertise in Northern Michigan
Our market research capabilities allow us to find the specific "sweet spot" for rental rates in Petoskey, Gaylord, and surrounding areas. We don't rely on broad national averages. Instead, we analyze local demand cycles to maximize your Gross Potential Income. This expertise is supported by a vetted contractor network that provides maintenance coordination at professional scales. By utilizing standardized maintenance systems, we prevent minor issues from escalating into major capital expenditures that could destabilize your cash reserves. Detailed financial reporting and accounting then allows you to track these performance trends over time, providing a clear view of your portfolio's trajectory.
Next Steps for Northern Michigan Investors
The transition from a hands-on landlord to a passive investor requires a shift in how you view your portfolio. Before finalizing any acquisition in Emmet or Charlevoix counties, a professional rental analysis is essential. This analysis verifies your assumptions regarding how to calculate rental property cash flow and identifies potential operational bottlenecks before they impact your liquidity. Our team specializes in providing the structured data needed to make these high-stakes decisions with confidence. To ensure your next investment is rooted in professional modeling rather than optimistic guesswork, contact Van Treese Management for a professional rental analysis today. This step is the foundation for building a resilient, cash-flowing portfolio in the complex 2026 real estate landscape.
Securing Your Northern Michigan Investment Strategy
Securing a sustainable investment future in Northern Michigan requires more than high-level estimations or optimistic projections. We've established that mastering how to calculate rental property cash flow involves a disciplined 5-step formula and a realistic assessment of local variables like seasonal vacancy and winterization costs. By distinguishing between paper profit and actual liquidity, you ensure the long-term financial integrity of your portfolio. Precision in these initial calculations acts as the foundation for every strategic decision you make.
To maximize these margins, you need a partner with the structural infrastructure and regional expertise to manage complex operational tasks. We provide detailed market research for Emmet and Charlevoix counties alongside 24/7 maintenance coordination to protect your margins from unexpected equipment failure. Our standardized systems ensure maximum efficiency across every residential or commercial unit you own. Optimize your Northern Michigan rental cash flow with Van Treese Management and transition from active management to passive wealth generation. Your real estate portfolio deserves the stability and precision of professional oversight.
Frequently Asked Questions
What is a good monthly cash flow for a rental property?
A sustainable monthly cash flow typically ranges between $100 and $300 per unit after all operating expenses and debt obligations are met. This figure varies based on your acquisition strategy and the specific market conditions in Traverse City or Petoskey. We prioritize consistency over high-risk projections. A lower cash flow might be acceptable if the asset is in a premium location with high appreciation potential, provided the property maintains positive liquidity through seasonal shifts.
Does rental property cash flow include the mortgage principal?
Cash flow calculations must account for the entire mortgage payment, which includes both principal and interest. While the principal portion technically increases your equity and net worth, it remains an outflow of liquid capital. When you analyze how to calculate rental property cash flow, you subtract the total debt service from your Net Operating Income. This ensures your final figure represents the actual bankable cash remaining for reinvestment or personal use.
How do I calculate cash flow if the property is vacant?
During periods of vacancy, your Effective Gross Income drops to zero while fixed expenses and debt service remain constant. You calculate this by subtracting your total operating expenses and mortgage payments from your other income sources, if any exist. This result will be negative, representing the capital injection required to maintain the asset. We mitigate this risk by applying a 5 to 10 percent vacancy factor to all annual projections for properties in Boyne City or Gaylord.
What is the 1% rule and is it still relevant in 2026?
The 1% rule suggests that a property's monthly rent should equal at least one percent of its total purchase price. In the 2026 Northern Michigan market, this benchmark is increasingly difficult to achieve due to elevated property values and interest rates exceeding 7 percent. While it serves as a quick screening tool, it's often too reductive for professional analysis. We recommend using the detailed 5-step formula to determine actual profitability rather than relying on outdated shortcuts.
Should I include income taxes in my cash flow calculation?
Standard cash flow models focus on "pre-tax cash flow" because individual tax liabilities vary significantly based on your overall income and filing status. You should include property taxes as a fixed operating expense, but personal income taxes are typically handled during year-end accounting. The Qualified Business Income deduction available in 2026 can impact your net profitability. We advise consulting with a tax professional to understand how depreciation and deductions affect your final after-tax position.
How does snow removal affect cash flow in Northern Michigan?
Snow removal is a critical operational expense in Emmet and Charlevoix counties that directly impacts your monthly margins. Depending on the lease structure, the landlord may be responsible for clearing driveways and walkways to maintain safety and compliance. This seasonal cost must be averaged across the entire fiscal year or handled through a dedicated reserve fund. Neglecting to account for Northern Michigan's winter requirements can lead to structural deficits during peak snowfall months in Petoskey or Indian River.
What is the difference between cash flow and ROI?
Cash flow represents the absolute dollar amount remaining after all expenses, whereas Return on Investment (ROI) is a percentage reflecting the efficiency of your capital. ROI accounts for total gains, including equity build-up through principal reduction and potential appreciation. Cash flow is the primary metric for immediate liquidity and operational stability. Understanding how to calculate rental property cash flow allows you to determine if the asset can sustain itself without requiring external capital injections.
Can professional property management actually increase my cash flow?
Professional management often increases net cash flow by optimizing revenue and reducing operational leakage. Our standardized systems in Grand Rapids and Traverse City minimize vacancy periods through aggressive marketing and rigorous tenant screening. We leverage a vetted contractor network to prevent minor repairs from becoming expensive capital expenditures. While the management fee is an expense, the resulting increase in Effective Gross Income and reduction in turnover costs often produce a higher net yield for the investor.